
Global carbon dioxide emissions
According to the latest Global Carbon Budget (2026), global carbon emissions from fossil fuels are projected to decrease by 0.4% in 2026, driven by expansion of solar and wind power and a widespread decrease in oil emissions, likely a short-term response to the energy shock triggered by the Iran conflict.
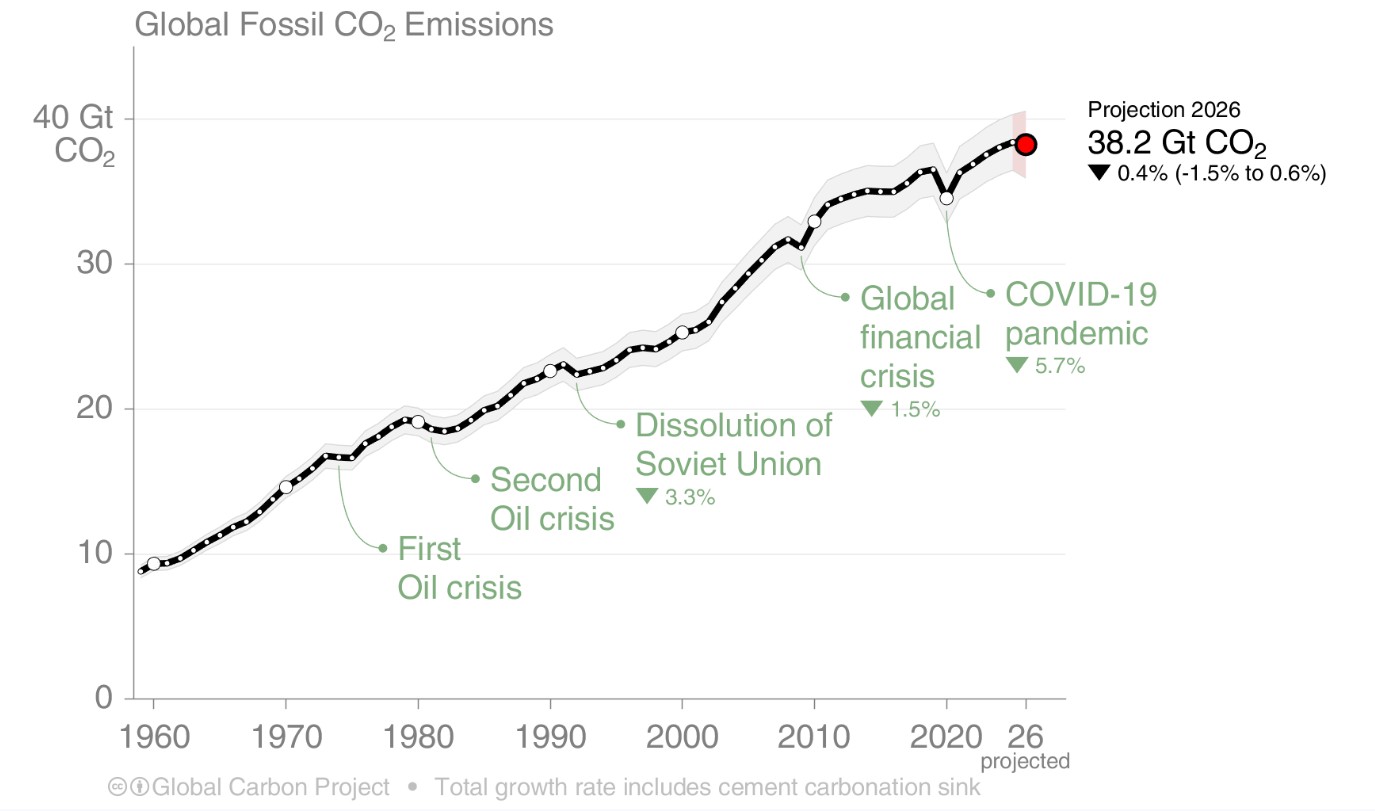
The 2026 Global Carbon Budget projects 38.2 billion tonnes of fossil carbon dioxide (CO2) emissions this year.
However, with emissions from land-use change (such as deforestation) projected to increase slightly this year, total CO2 emissions are projected to be 43.3 billion tonnes in 2026 – up from 42.8 billion tonnes last year.
The remaining carbon budget (the amount of CO2 that can be emitted before warming reaches 1.5°C above pre-industrial levels) is now 150 billion tonnes – equivalent to less than four years of emissions at the current rate.
The trend in total emissions from both fossil fuels and land use change has grown by 0.3 per cent per year on average over the last decade, compared to 1.7 per cent the previous decade.
The report also assesses natural “sinks” (absorption of CO2 by land and ocean). It finds that the land sink returned to former levels after a severe weakening during the 2023-24 El Niño weather pattern.
However, the powerful 2026 El Niño is expected to have a significant impact in the coming year. The land and ocean have taken up 49% of total anthropogenic emissions in the past decade, but both sinks are negatively impacted by climate change.
The concentration of CO2 in the atmosphere is set to reach 427.7 parts per million in 2026, 54% above pre-industrial level. Atmospheric concentration is projected to grow by 2.2 ppm in 2026, further increasing the human influence on climate.
Changes in global fossil CO2 emissions
Across the globe, the picture for the top emitting countries varies.
China’s fossil emissions (32 per cent of global fossil emissions) are projected to decrease by 0.9 per cent on 2025 levels, following two years of low emissions growth. While China produces 32% of global fossil emissions, it is also the country most active in deploying clean technologies and increasing carbon sinks through reforestation.
The United States’ emissions (13 per cent of global fossil emissions) are projected to increase by 1.3 per cent, mainly due to a decrease in coal emissions (which spiked last year due to high natural gas prices and cold weather).
India’s emissions (8 per cent of global fossil emissions) are projected to increase by 4.4 per cent over 2025. This is above the 3.5 per cent average annual growth over the last decade, partly reflecting a rebound from low emissions growth in 2025. Since the government fixes petrol and diesel prices, the closure of the Strait of Hormuz has not led to a drop in road-transport emissions, but consumption of other oil products has declined.
European Union emissions (6 per cent of global fossil emissions) are projected to decrease by 1.5 per cent over 2025, below the trend of the past decade. While diesel prices have risen in some countries, others have introduced measures to keep prices down. Record heat in summer in Western Europe led to higher demand for cooling. Uncertainty is high, particularly with emissions from oil.
In Japan (2.5% of global fossil emissions), emissions in 2026 are projected to decrease by 1 per cent. The government of Japan also fixes road-fuel prices, so there has been no direct consequence of the global supply issues for road-transport emissions, but oil use in the petrochemicals sector dropped sharply for a short period.
For the rest of the world (38% of global fossil emissions), emissions in 2026 are projected to decrease by 0.7% over 2025. The largest component of the decline is in oil, likely driven by increased prices and global supply constraints.
The number of countries reducing their emissions while growing their economies is increasing: 40 economies have decreased their fossil CO2 emissions significantly while growing their economies in the decade 2016-2025, nearly twice as many as during the previous decade (2006-2015; 22 countries). These 40 countries account for 26% of current global fossil CO2 emissions. Emissions reductions expanded to 59 countries in all continents for the shorter 2019-2025 time period, although not all of these trends are significant.
Avoided emissions from solar and wind power and electric vehicles are projected to grow about 0.5 GtCO2 in 2026, offsetting about two-thirds of the emissions growth from rising demand.
The land and ocean sinks have been relatively stagnant for a decade or more, taking up 49% of anthropogenic emissions in the past decade, 22% and 27% respectively. The land carbon sink weakened substantially in 2024 due to El Niño conditions. It returned fully in 2025 to its pre-El Niño levels, but the effect of the 2026-2027 El Niño is expected in 2027.
The remaining carbon budget to limit global warming to 1.5°C is virtually exhausted. For a 50% likelihood of limiting warming below 1.5°C, the remaining budget is 150 GtCO2, equivalent to less than 4 years at the 2026 emissions levels. The remaining carbon budgets to limit warming to 1.7°C and 2°C above the 1850-1900 level have been reduced to 510 GtCO2 and 1035 GtCO2, 12 years and 24 years at 2026 emissions levels respectively.
Global carbon dioxide emissions
According to the latest Global Carbon Budget (2026), global carbon emissions from fossil fuels are projected to decrease by 0.4% in 2026, driven by expansion of solar and wind power and a widespread decrease in oil emissions, likely a short-term response to the energy shock triggered by the Iran conflict.
The 2026 Global Carbon Budget projects 38.2 billion tonnes of fossil carbon dioxide (CO2) emissions this year.
However, with emissions from land-use change (such as deforestation) projected to increase slightly this year, total CO2 emissions are projected to be 43.3 billion tonnes in 2026 – up from 42.8 billion tonnes last year.
The remaining carbon budget (the amount of CO2 that can be emitted before warming reaches 1.5°C above pre-industrial levels) is now 150 billion tonnes – equivalent to less than four years of emissions at the current rate.
The trend in total emissions from both fossil fuels and land use change has grown by 0.3 per cent per year on average over the last decade, compared to 1.7 per cent the previous decade.
The report also assesses natural “sinks” (absorption of CO2 by land and ocean). It finds that the land sink returned to former levels after a severe weakening during the 2023-24 El Niño weather pattern.
However, the powerful 2026 El Niño is expected to have a significant impact in the coming year. The land and ocean have taken up 49% of total anthropogenic emissions in the past decade, but both sinks are negatively impacted by climate change.
The concentration of CO2 in the atmosphere is set to reach 427.7 parts per million in 2026, 54% above pre-industrial level. Atmospheric concentration is projected to grow by 2.2 ppm in 2026, further increasing the human influence on climate.
A black line with white markers shows a long-term increase in emissions from about 9 Gt CO₂ in 1960 to around 38 Gt CO₂ in 2026. Although the overall trend is upward, several temporary declines are highlighted:
First oil crisis (mid-1970s), associated with a dip in emissions growth.
Second oil crisis (around 1980), associated with another decline.
Dissolution of the Soviet Union (early 1990s), marked with a 3.3% decrease.
Global financial crisis (around 2009), marked with a 1.5% decrease.
COVID-19 pandemic (2020), marked with the largest decline shown, a 5.7% decrease.
After each downturn, emissions resume rising and generally reach new highs. Emissions increase sharply between 2000 and 2010, from approximately 25 Gt CO₂ to more than 33 Gt CO₂, then continue upward with a temporary drop during the COVID-19 pandemic.
The 2026 estimate is highlighted with a red dot and a shaded uncertainty range. The graph projects global fossil CO₂ emissions in 2026 to be 38.2 Gt CO₂, representing a 0.4% decrease from 2025, with an uncertainty range from 1.5% lower to 0.6% higher.
Key message: Global fossil CO₂ emissions have risen substantially over the past six decades despite several major economic and geopolitical disruptions, and emissions in 2026 are projected to remain near record-high levels.
Changes in global fossil CO2 emissions
Across the globe, the picture for the top emitting countries varies.
China’s fossil emissions (32 per cent of global fossil emissions) are projected to decrease by 0.9 per cent on 2025 levels, following two years of low emissions growth. While China produces 32% of global fossil emissions, it is also the country most active in deploying clean technologies and increasing carbon sinks through reforestation.
The United States’ emissions (13 per cent of global fossil emissions) are projected to increase by 1.3 per cent, mainly due to a decrease in coal emissions (which spiked last year due to high natural gas prices and cold weather).
India’s emissions (8 per cent of global fossil emissions) are projected to increase by 4.4 per cent over 2025. This is above the 3.5 per cent average annual growth over the last decade, partly reflecting a rebound from low emissions growth in 2025. Since the government fixes petrol and diesel prices, the closure of the Strait of Hormuz has not led to a drop in road-transport emissions, but consumption of other oil products has declined.
European Union emissions (6 per cent of global fossil emissions) are projected to decrease by 1.5 per cent over 2025, below the trend of the past decade. While diesel prices have risen in some countries, others have introduced measures to keep prices down. Record heat in summer in Western Europe led to higher demand for cooling. Uncertainty is high, particularly with emissions from oil.
In Japan (2.5% of global fossil emissions), emissions in 2026 are projected to decrease by 1 per cent. The government of Japan also fixes road-fuel prices, so there has been no direct consequence of the global supply issues for road-transport emissions, but oil use in the petrochemicals sector dropped sharply for a short period.
For the rest of the world (38% of global fossil emissions), emissions in 2026 are projected to decrease by 0.7% over 2025. The largest component of the decline is in oil, likely driven by increased prices and global supply constraints.
The number of countries reducing their emissions while growing their economies is increasing: 40 economies have decreased their fossil CO2 emissions significantly while growing their economies in the decade 2016-2025, nearly twice as many as during the previous decade (2006-2015; 22 countries). These 40 countries account for 26% of current global fossil CO2 emissions. Emissions reductions expanded to 59 countries in all continents for the shorter 2019-2025 time period, although not all of these trends are significant.
Avoided emissions from solar and wind power and electric vehicles are projected to grow about 0.5 GtCO2 in 2026, offsetting about two-thirds of the emissions growth from rising demand.
The land and ocean sinks have been relatively stagnant for a decade or more, taking up 49% of anthropogenic emissions in the past decade, 22% and 27% respectively. The land carbon sink weakened substantially in 2024 due to El Niño conditions. It returned fully in 2025 to its pre-El Niño levels, but the effect of the 2026-2027 El Niño is expected in 2027.
The remaining carbon budget to limit global warming to 1.5°C is virtually exhausted. For a 50% likelihood of limiting warming below 1.5°C, the remaining budget is 150 GtCO2, equivalent to less than 4 years at the 2026 emissions levels. The remaining carbon budgets to limit warming to 1.7°C and 2°C above the 1850-1900 level have been reduced to 510 GtCO2 and 1035 GtCO2, 12 years and 24 years at 2026 emissions levels respectively.
Related research
Find out more about how we monitor atmospheric carbon dioxide and our research helping to lower emissions.